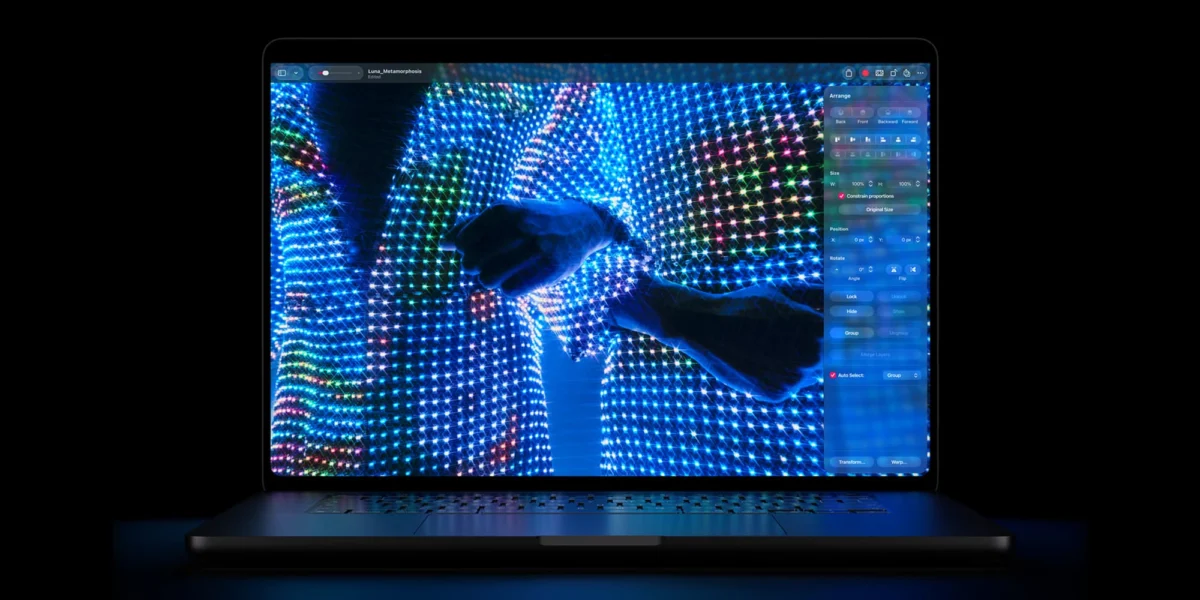
Apple’s official introduction of its redesigned MacBook Pro—featuring both advanced tandem OLED display technology and the company’s first-ever touchscreen integration in a Mac—has fundamentally altered the trajectory of the personal computer industry. Following years of speculation, supply chain leaks, and strategic roadmaps, the launch has triggered a massive ripple effect across the global display and notebook manufacturing sectors. Market intelligence firm TrendForce has released an extensive report examining how Apple’s long-awaited entry into the OLED laptop space will influence shipments, manufacturing contracts, and consumer adoption through the end of the decade.
The arrival of the new MacBook Pro marks a decisive turning point for display technology in portable computing. Historically, the adoption of organic light-emitting diode (OLED) panels in laptops has been championed by Windows-based original equipment manufacturers (OEMs), including Lenovo, HP, and ASUS. These brands successfully introduced OLED options across various price tiers to capture creative professionals and multimedia enthusiasts. However, market penetration remained relatively constrained due to the absence of a major industry bellwether. With Apple now committing its flagship professional lineup to OLED, market dynamics are shifting rapidly, signaling an era where self-emissive displays transition from niche luxury features to mainstream industry standards.
Chronology and Evolution of Apple’s OLED Roadmap
The path to Apple’s first OLED MacBook Pro has been years in the making, defined by meticulous supply chain preparations and iterative product development cycles. Rumors regarding Apple’s transition away from Mini-LED technology first intensified in earnest during 2024, following the successful debut of tandem OLED screens in the M4 iPad Pro lineup. This pioneering technology utilizes two stacked emissive layers, allowing displays to achieve significantly higher peak brightness levels, enhanced energy efficiency, and extended panel longevity compared to traditional single-layer OLED configurations, all while retaining signature deep blacks and infinite contrast ratios.

By September 2025, industry reports from specialized publications such as The Elec indicated that major panel suppliers, notably Samsung Display, were ramping up preparations to initiate mass production of 14-inch and 16-inch OLED panels tailored specifically for Apple’s upcoming MacBook Pro redesign. Analysts at the time estimated an initial annual manufacturing output ranging between 2 million and 3 million units to meet projected demand.
As the supply chain mobilized, market analysts adjusted their long-term forecasts. In late 2025, TrendForce predicted that global OLED notebook market share would surge toward the 12% threshold by 2027 and 2028, heavily catalyzed by Apple’s imminent market entry. Subsequent roadmap updates published earlier in the year clarified Apple’s broader hardware trajectory, pointing to a dual-phase rollout: the MacBook Pro arriving in 2026, followed eventually by the MacBook Air, which faced a slight internal timeline adjustment pushing its estimated debut to 2029.
Sales Projections and Market Impact Through 2027
The newly published TrendForce report details specific shipment trajectories for Apple and the broader industry in the wake of the October announcement. For 2027, Apple is projected to ship between 1.2 million and 1.5 million units of the new touchscreen OLED MacBook Pro. While these figures represent a strong initial volume for a high-end professional device, analysts emphasize that near-term consumer replacement cycles may experience temporary friction.
The primary moderating factor identified by TrendForce is the product’s premium market positioning. With the 14-inch model carrying a starting price of $2,899, and with Apple initially maintaining a transitional period where older Mini-LED configurations remain available in the marketplace, immediate upgrades among existing pro-tier users may occur gradually. Nevertheless, the psychological and commercial weight of Apple’s endorsement is expected to drive robust indirect benefits.

On a macro level, the global OLED notebook sector is experiencing unprecedented acceleration. TrendForce data indicates that worldwide OLED laptop shipments grew by nearly 40% year-over-year in 2026, with an anticipated matching expansion of more than 40% throughout 2027. Industry analysts note that Apple’s market entry provides vital validation, compelling competing PC manufacturers to prioritize OLED integration in their forthcoming hardware roadmaps and accelerating consumer familiarity with the technology.
Supply Chain Competition for Future MacBook Air Models
Beyond the immediate success of the MacBook Pro, the broader supply chain is already fiercely contesting future contracts for Apple’s upcoming consumer-tier hardware. With the OLED MacBook Air targeted for a 2029 release, display manufacturing giants are aggressively scaling their technological capabilities to secure lucrative orders from Cupertino.
According to industry trackers, three major display heavyweights—LG Display, BOE, and TCL CSOT—are currently locked in intense competition to become primary panel suppliers for the future MacBook Air. Each of these manufacturers has poured substantial capital into expanding their respective 8.5-generation and higher-generation OLED production lines, aiming to achieve the strict yield rates, thinness profiles, and cost efficiencies demanded by Apple for its high-volume consumer notebooks.
Broader Industry Outlook Toward 2030
Looking toward the end of the decade, the integration of OLED technology into portable computers is projected to reshape the entire hardware landscape. TrendForce’s long-term econometric models estimate that global OLED notebook shipments will maintain a steep upward trajectory, ultimately reaching 46.6 million units by 2030.
While annual growth rates are expected to peak at 42.8% in 2028—fueled by the combined momentum of Windows OEM expansion and Apple’s deeper catalog integration—subsequent growth is projected to stabilize moderately, settling at an estimated 30.8% year-over-year increase by 2030 as market saturation approaches.
Ultimately, Apple’s transition to OLED represents far more than a simple hardware refresh. By establishing tandem OLED and touch interfaces as foundational elements of its pro notebook ecosystem, Apple has solidified a new technological baseline for the entire computer industry. As manufacturing capacities scale and economies of scale take hold over the next several years, the display standards introduced by this launch will inevitably cascade downward into more accessible consumer price points, permanently transforming how users interact with portable computing devices.