
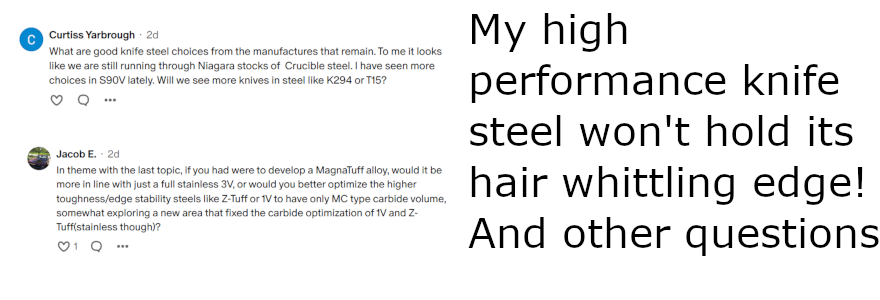
The global landscape of metallurgy, particularly within the specialized niche of high-performance cutlery steel, has reached a point of significant scrutiny as of October 2026. Recent inquiries regarding the sustainability of supply chains for premium knife alloys have prompted a comprehensive review by industry experts, including metallurgist Larrin Thomas, to address concerns about potential resource depletion, technological plateaus, and the future trajectory of blade material development. This analysis seeks to clarify whether the rapid innovation seen over the last two decades is approaching a natural limit or if the industry is merely transitioning into a new phase of refinement.
Contextualizing the Modern Steel Supply Chain
The production of premium knife steel—often characterized by complex powder metallurgy processes and high concentrations of vanadium, niobium, and chromium—relies on a global supply of specialty elements. The "super steel" era, which gained significant momentum in the early 2000s, has been defined by the pursuit of alloys that offer an optimized balance of edge retention, toughness, and corrosion resistance.
However, as the demand for high-end tactical, culinary, and outdoor tools increases, questions have surfaced regarding the availability of the raw materials required to produce these sophisticated compositions. Unlike bulk carbon steel, super steels are dependent on specific alloying elements whose market prices and availability fluctuate based on geopolitical stability and industrial demand from the aerospace and automotive sectors. Currently, there is no evidence of a systemic shortage of the base elements—such as iron, carbon, or alloying agents—necessary to produce premium cutlery steels. Rather, the bottleneck for consumers is largely defined by production capacity at specialized mills and the economic feasibility of producing niche batches for the knife industry.
Chronology of Innovation and Production
To understand the current state of the industry, one must look at the progression of alloy development over the last twenty years:
- 2005–2010: The Rise of Powder Metallurgy. This period saw the mass adoption of CPM (Crucible Particle Metallurgy) processes, allowing for the creation of highly wear-resistant steels like S30V and later S35VN.
- 2011–2018: The Pursuit of "Super" Performance. Manufacturers pushed the limits of carbide volume, leading to the introduction of high-vanadium steels like M390 and CPM-20CV, which redefined consumer expectations for edge retention.
- 2019–2024: Diversification and Specialized Heat Treatment. As the limits of "more alloy" were reached, the focus shifted toward optimizing heat treatment protocols and grain structure refinement, exemplified by the increased understanding of austenitizing and quenching cycles.
- 2025–Present: The Sustainability and Scaling Phase. The industry is now grappling with the costs of high-performance materials and the logistical challenges of maintaining consistent supply chains for smaller boutique knife manufacturers.
Supporting Data on Material Constraints
The perception that we are "running out" of steel is often conflated with the challenges of accessing high-end alloys. Metallurgical data suggests that while the chemistry of these steels is well-understood, the manufacturing process is incredibly energy-intensive.
The production of powder metallurgy steel requires high-pressure gas atomization, followed by Hot Isostatic Pressing (HIP). These facilities are limited in number globally. When aerospace companies or the automotive industry place large orders for tool steels or specialized alloys, the capacity available for the cutlery industry can tighten. Data from the global specialty steel market indicates that while total output has grown by approximately 3.2% annually, the specific demand for high-vanadium cutlery grades has seen a sharper spike, leading to occasional backlogs. These backlogs are not indicative of an absolute shortage of the metal itself, but rather a temporary constraint in the specialized manufacturing pipeline.
Expert Analysis and Industry Response
Metallurgists note that the industry is not facing a resource exhaustion crisis, but rather a shift in research and development (R&D) objectives. In recent discourse, the focus has moved away from simply adding more alloying elements to improve hardness. Adding more chromium or vanadium often leads to diminishing returns, where the steel becomes increasingly brittle and difficult to sharpen.
Current trends indicate that the "next frontier" is not the invention of a "magic" new element, but rather the improvement of existing steel performance through:
- Cryogenic Processing: Refining the martensitic transformation to ensure maximum hardness and stability.
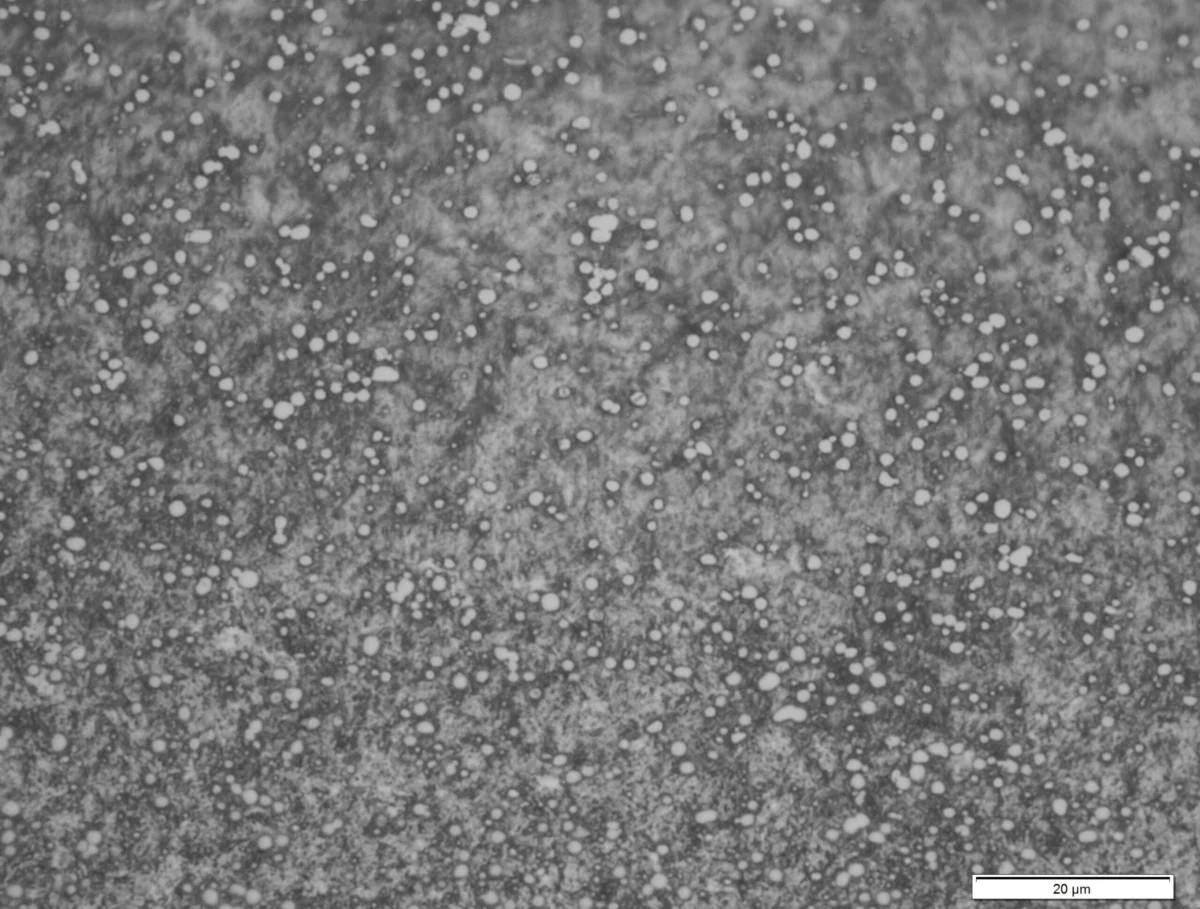
- Grain Boundary Engineering: Controlling the microscopic structure of the steel to optimize toughness without sacrificing wear resistance.
- Advanced Quenching Techniques: Utilizing computer-controlled cooling to prevent micro-cracking in high-alloy steels.
By focusing on these procedural improvements, the industry can continue to improve knife performance without requiring new, scarce raw materials. This serves as a buffer against potential supply chain volatility.
Implications for the Consumer and Manufacturer
The implications for both custom knife makers and mass-market manufacturers are twofold. First, the cost of premium materials is likely to remain stable or potentially rise as energy costs for processing plants fluctuate. Second, consumers should anticipate that the pace of "revolutionary" new steel releases will slow down. The era of a new "best steel ever" being released every six months is likely coming to a close. Instead, the industry is entering an era of maturity where the focus is on the standardization of heat treatments and the mastery of current alloys.
For the end-user, this means that the current market offerings—such as MagnaCut, S45VN, and high-performance tool steels—are likely to remain the industry standard for the foreseeable future. There is no looming "steel apocalypse," but there is a clear necessity for the industry to manage its resources more efficiently. Manufacturers who can leverage precise heat treatment techniques will likely outperform those who simply rely on the marketing of "new" or "exclusive" proprietary steels.
Conclusion: The Future of Metallurgy
The inquiry into whether we are running out of premium knife steel serves as a reminder of the complexity behind everyday tools. The integration of high-level metallurgy into the knife industry has been a remarkable success story of the early 21st century. While the industry faces logistical challenges—namely, competition for production time at large-scale mills—the foundation of modern cutlery remains secure.
The trajectory of the next decade will likely be defined by a shift from raw chemistry to refined processing. By optimizing existing resources and focusing on the science of heat treatment, the knife industry can continue to deliver high-performance products to a global market. The "nerd" culture surrounding knife steel, which prioritizes empirical testing and objective data, remains the most effective mechanism for ensuring that manufacturers remain accountable and that the quality of tools remains high. As long as the demand for precision and durability exists, the metallurgical community will continue to find ways to meet that need, ensuring that the development of superior blade materials remains a sustainable, albeit evolving, discipline.