For years, the prospect of Chinese automotive giants establishing a foothold in the North American market seemed like an inevitability—a logical progression in the global expansion strategy of manufacturers like BYD, SAIC, and NIO. However, the late 2010s and early 2020s saw a drastic pivot in U.S. industrial policy. What began as a series of trade disputes evolved into a comprehensive defensive strategy aimed at protecting the domestic manufacturing base. Today, the U.S. automotive landscape is defined by aggressive tariff structures, stringent supply chain requirements, and comprehensive prohibitions on hardware and software developed by Chinese entities. Despite this "frosty" diplomatic climate, recent comments from President-elect Donald Trump have injected a new, albeit complex, variable into the debate, suggesting a potential pathway for Chinese automakers to operate domestically, provided they adhere to specific "local-hire" mandates.
A Shifting Stance on Foreign Direct Investment
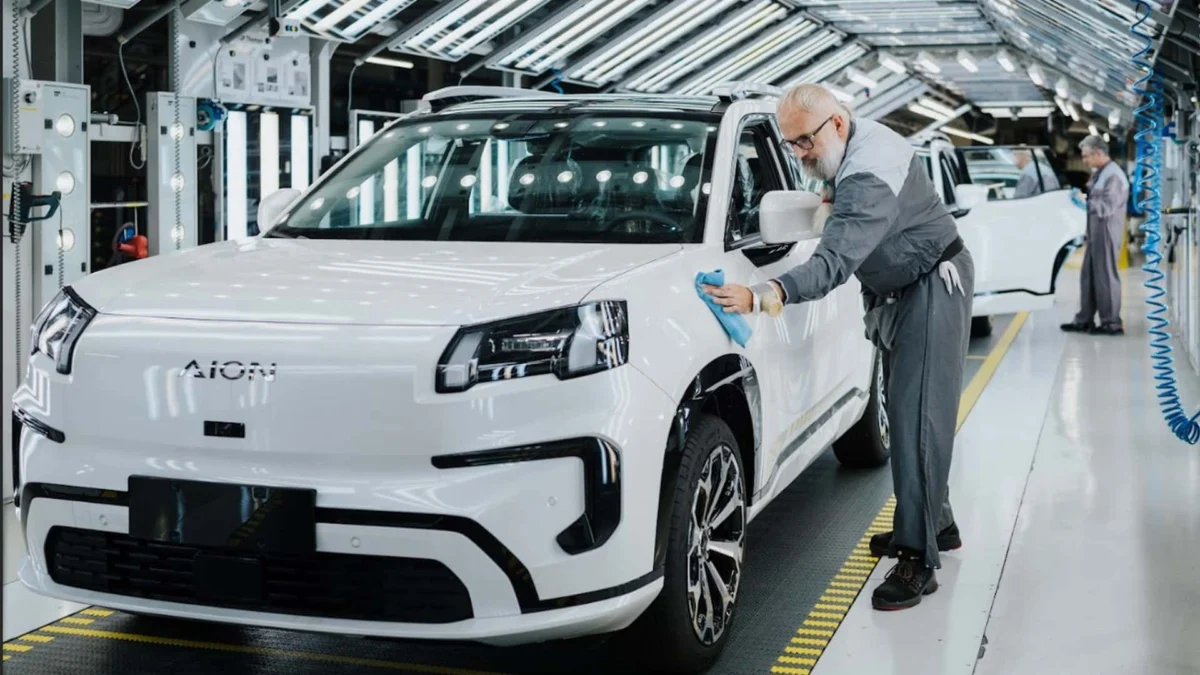
During an appearance on Fox News’ The Ingraham Angle last Friday, Donald Trump signaled a potential softening of his long-standing protectionist stance regarding Chinese manufacturers. When asked about the possibility of Chinese firms entering the U.S. market, Trump indicated that he would be amenable to such moves under one primary condition: the vehicles must be built domestically.
"If China wanted to come in and open a plant to build their cars here, I’d be okay with that," Trump stated during the interview. He drew a direct parallel to the historical success of Japanese automakers, such as Toyota, Honda, and Nissan, which have operated assembly plants in the United States for decades. "Japan does it, but they hire our people. The big thing is they hire our people," he added. However, the President-elect was quick to draw a red line regarding regional supply chains, explicitly stating his opposition to companies using Mexico as a "backdoor" to circumvent U.S. trade rules and tariffs by assembling components south of the border before shipping finished vehicles into the U.S. market.
The Legislative and Regulatory Reality
While Trump’s rhetoric suggests a pragmatic, transactional approach to trade, the current regulatory framework remains heavily tilted against Chinese involvement. The U.S. government has maintained a largely bipartisan consensus on the risks associated with Chinese technology in vehicles. This is best exemplified by the Department of Commerce’s recent initiatives.
Beginning in 2027, the U.S. will implement a ban on vehicles featuring Chinese-developed software, followed by a prohibition on Chinese-made hardware in 2030. These regulations are not merely hypothetical; they have already had tangible impacts on the market. Polestar, the Swedish electric vehicle brand with significant ties to Chinese ownership (Geely), recently saw its access to the U.S. market severely constrained due to these regulatory hurdles. Similarly, companies like Mercedes-Benz have faced intense scrutiny regarding their technical partnerships, highlighting the difficulty even established Western manufacturers face when attempting to integrate Chinese expertise into their supply chains.
The legislative atmosphere is further complicated by recent actions from officials like Secretary of Transportation Sean Duffy. Last week, Duffy issued a scathing public critique of Ford Motor Company’s licensing agreement with CATL, the world’s largest battery manufacturer. Although Ford’s Michigan facility utilizes American labor to produce batteries, the facility operates using designs and proprietary knowledge licensed from the Chinese firm. The Department of Transportation’s aggressive stance against this partnership indicates that the federal government is wary of any "Chinese-adjacent" manufacturing, even when the final product is assembled on American soil.
Chronology of Escalating Tensions
The path to this moment has been marked by a series of escalating measures:
- 2018-2019: The initiation of broad trade tariffs on Chinese goods, which significantly increased the cost of importing vehicles and components.
- 2023-2024: Heightened focus on national security, with lawmakers labeling Chinese "connected vehicles" as potential tools for data collection and surveillance.
- Late 2024: Senator Elissa Slotkin of Michigan spearheaded efforts to draft legislation that would effectively ban Chinese-branded vehicles from the U.S. market permanently, regardless of where they are assembled.
- January 2025: The Department of Commerce formalized its roadmap for the 2027 software and 2030 hardware bans, effectively creating a "soft" exit for brands heavily reliant on Chinese components.
- Late January 2025: Trump’s public pivot, creating a point of contention with his own party’s legislative wing as he prepares to meet with President Xi Jinping.
The Economic Implications of Localization
The debate surrounding Chinese automotive entry is deeply rooted in the concept of "localization." Proponents of allowing Chinese firms to build in the U.S. argue that it would create thousands of manufacturing jobs, revitalize industrial "rust belt" regions, and force domestic automakers to innovate faster to compete with the high-efficiency, low-cost production methods mastered by Chinese firms.
However, critics, including members of the Senate and labor unions, argue that allowing Chinese investment is a Trojan horse. They contend that even if the cars are built in the U.S., the intellectual property remains in China, and the supply chain would likely remain dependent on Chinese-subsidized raw materials. This, they argue, would prevent U.S. companies from ever achieving true independence in the EV sector.
Data from the automotive sector suggests that China is currently leading in the global export market. In 2024, China exported a record number of vehicles, surpassing historical leaders like Japan and Germany. The sheer scale of China’s production capacity—often bolstered by heavy state subsidies—is what drives the fear among Western policymakers that U.S. manufacturers cannot compete on price, even with a level playing field.
Political Friction and the Road Ahead
The tension between Trump’s "America First" manufacturing mandate and the broader national security concerns raised by his own political allies creates an environment of profound uncertainty for the auto industry. If a deal is struck during the upcoming summit with President Xi, it could lead to a massive influx of foreign direct investment in U.S. manufacturing hubs.
However, any such deal would face significant legal and political challenges. If the current administration or Congress remains committed to the 2027/2030 bans, even a presidential directive might not be enough to clear the path for Chinese brands. The legal battleground would likely be defined by "national security exceptions" and trade law, which would take years to resolve in the courts.
Furthermore, the domestic automotive industry—the "Detroit Three" (Ford, General Motors, and Stellantis)—has invested billions in pivoting toward EV production. These companies are likely to lobby heavily against any policy that allows Chinese competitors to bypass the current protective barriers. They argue that they have played by the rules and invested in domestic supply chains, and that allowing competitors who have benefited from non-market practices to enter the U.S. market would be fundamentally unfair.
Conclusion: A Strategic Crossroads
As the U.S. moves into the latter half of the decade, the question of whether to engage with or isolate the Chinese automotive industry remains one of the most significant geopolitical issues in the global economy. Trump’s stated willingness to allow Chinese plants in the U.S. represents a potential shift toward a more pragmatic, job-focused trade policy. Yet, the deep-seated concerns over data security, intellectual property theft, and the long-term viability of American manufacturing continue to act as a formidable buffer.
The coming weeks, punctuated by high-level diplomatic meetings, will be a bellwether for the future of the American auto industry. Whether the U.S. chooses to integrate Chinese manufacturing under strict American oversight or opts for a more isolationist approach will define the trajectory of the automotive market for the next generation. For now, automakers in both nations remain in a holding pattern, waiting to see if the political rhetoric of today will translate into the regulatory shifts of tomorrow.